 LONG-TERM CARE INSURANCE
Using Long-Term Care Insurance for Home Care
The first step is to find out what your long-term care insurance (LTCi) policy covers.
Request a Free Policy ReviewYou may have paid long-term care insurance premiums for years without opening the policy. Then a parent falls, or a new diagnosis changes what an ordinary day looks like, and you need to know if your policy will pay for help at home.
For many families, it can. The first step is to find out what your long-term care insurance (LTCi) policy covers. This applies whether the policy is yours, you’re helping an aging parent, or you’re a case manager or agent guiding a family.
Quick Answer: Does Long-Term Care Insurance Cover Home Care?
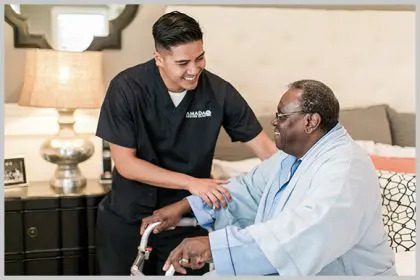
Many long-term care insurance policies cover home care, but your contract decides what yours will pay for. Most policies pay for help with activities of daily living, such as bathing, dressing, and toileting, once a licensed health care practitioner signs off that you need it. Some older policies only cover nursing home care, so check yours before you start planning.
In most policies, benefits begin after you meet a benefit trigger and complete a waiting period called an elimination period. Your policy also sets a daily or monthly maximum and a total benefit amount.
Medicare does not pay for ongoing personal care at home when that is the only care someone needs. If your family has an LTC insurance policy, it may be one of the most useful resources for paying for home care.
Amada Senior Care offers a complimentary policy review to help you understand what your coverage includes.
What Home Care Services Can Long-Term Care Insurance Cover?
LTCi policies that include home care cover non-medical help that keeps a senior safe at home. Depending on your contract, covered services may include the following:
Help With Activities of Daily Living
Caregivers provide hands-on or standby help with bathing, dressing, eating, toileting, continence care, and mobility needs. Most home care benefits center on this help.
Supervision for Cognitive Impairment
If your loved one is living with Alzheimer’s disease or another form of dementia, many policies pay for a caregiver to watch over them and give gentle reminders, such as when to eat or take a shower. Your loved one may qualify for this help even if they can still do some daily tasks on their own.
Amada trains its caregivers to support seniors living with dementia at home. Some Amada offices also help eligible families access the Medicare Guiding an Improved Dementia Experience (GUIDE) Model, which adds care coordination and caregiver support.
When staying home is no longer the right fit, many LTCi policies also help pay for a memory care community. Amada can help you find assisted living and memory care near you.
Homemaker Services
Some policies also pay for help around the house, such as cooking meals, light cleaning, laundry, and running errands. These tasks are called instrumental activities of daily living (IADLs). In most cases, a policy covers this help only if your loved one also needs help with personal care, like bathing or dressing.
Respite Care
Many policies include a respite care benefit, which pays for a professional caregiver to step in for a short time so a family caregiver can take a break, whether they need rest, a trip, or time to manage their own health.
Other Policy-Dependent Benefits
Depending on the contract, benefits may also help pay for adult day services, a care coordinator, home safety modifications, or medical alert equipment. Be sure to review the policy language or ask a care advisor to check it with you.
How Do You Qualify for Long-Term Care Insurance Benefits for Home Care?
You qualify for benefits when you meet your policy’s benefit trigger, the condition you must meet before the insurer begins paying. Most policies sold today use one of two triggers:
- You need help with at least two activities of daily living, and that need is expected to last at least 90 days.
- You have a severe cognitive impairment and need substantial supervision to stay safe.
In most policies, a licensed health care practitioner, such as a doctor, nurse, or social worker, must certify that you meet the trigger. Many insurers also send their own nurse to complete an in-home assessment and ask for a written plan of care. A diagnosis alone does not establish eligibility. The insurer reviews the assessment against your policy’s terms and decides whether to approve the claim.
Activities of Daily Living (ADLs)
ADLs are the basic self-care tasks that most LTCi policies use to measure need. Standard policies list six:
| ADL | What help can look like at home |
|---|---|
| Bathing | Getting in and out of the tub or shower safely, washing, and drying off |
| Dressing | Choosing clothes, managing buttons and zippers, putting on shoes or braces |
| Eating | Help bringing food to the mouth or using utensils (meal preparation counts separately) |
| Toileting | Getting to and from the toilet, sitting and standing, and personal hygiene afterward |
| Continence | Managing bladder and bowel control, including changing incontinence supplies |
| Transferring | Moving from a bed to a chair, or from a wheelchair to a car seat |
Some older policies list ambulation (walking) or grooming instead of continence or transferring. The insurer goes by the definitions in your policy. Help can mean hands-on assistance or standby assistance, where a caregiver stays within arm’s reach in case your loved one starts to fall.
Severe Cognitive Impairment
A person living with Alzheimer’s disease or another form of dementia may still be able to bathe and dress, but forget to turn off the stove or wander from home. Many policies treat severe cognitive impairment as its own benefit trigger.
The need for supervision can qualify on its own, even when your loved one still manages most ADLs. Most insurers confirm cognitive impairment with standardized memory and reasoning tests.
Elimination or Waiting Periods
The elimination period is the number of days you must wait after meeting the benefit trigger before the policy starts paying. Common elimination periods range from 0 to 100 days, where 90 days is typical. Your family pays for care during that time unless the policy says otherwise.
Check how your policy counts those days. Some policies count calendar days. Others count only the days you receive paid care. With a 90-day service elimination period, a parent who receives care three days a week could wait about seven months before benefits begin.
Ask the insurer to explain how your policy counts days and to confirm it in writing. Some policies waive the elimination period for home care, so check that too.
What May Not Be Covered?
Knowing what your policy limits early helps you plan without surprises. Depending on your contract, LTCi may not pay for:
- Care before the elimination period ends.
Your family covers these costs unless the policy waives the waiting period. - Care from an ineligible provider.
Many policies require care from a licensed home care agency. Some exclude family members or independent caregivers you hire on your own. - Services the policy does not list.
Some policies exclude homemaker help, companionship, or transportation when your loved one needs no other care. - Care above the daily or monthly maximum.
If long-term care costs are more than your benefit limit, you pay the difference. - Care after benefits run out.
Most policies have a total lifetime benefit, sometimes called a benefit pool. Once you use it, payments stop. - Specific exclusions.
Many policies exclude care related to certain preexisting conditions during an initial period, along with care outside the United States.
If the insurer denies a claim, you can ask for a written explanation and, in most cases, appeal the decision. A care advisor can help you understand the reason and gather any missing documentation.
Home Care vs. Home Health Care
Home care and home health care sound alike, but they meet different needs and rely on different payment sources. LTCi most often pays for non-medical home care.
| Home care (non-medical) | Home health care (medical) | |
|---|---|---|
| What it includes | Help with ADLs, supervision, meals, light housekeeping, errands, companionship | Skilled nursing, wound care, injections, physical, occupational, or speech therapy |
| Who provides it | Trained caregivers and home health aides employed by a home care agency | Registered nurses, licensed therapists, and aides working under a skilled care plan |
| How long it lasts | As long as the need continues, often ongoing | Short term, usually during recovery from an illness, injury, or hospital stay |
| Doctor’s order needed | Not for private pay; most LTCi policies require a practitioner’s certification | Yes |
| Common ways to pay | LTCi, private pay, VA benefits, some Medicaid programs | Medicare, Medicaid, private health insurance |
Amada Senior Care provides home care. If your loved one requires medical care, consult a licensed healthcare provider. Our home care guide explains both types of care in more detail.
Long-Term Care Insurance vs. Medicare vs. Medicaid vs. Private Health Insurance
Families often assume one of these programs will cover ongoing help at home. Each one serves a different purpose, and only LTCi pays for long-term personal care.
| Coverage type | What it is built for | Ongoing non-medical home care |
|---|---|---|
| Long-term care insurance | Paying for extended help with daily living at home, in assisted living, or in a nursing home | Often covered, within the policy’s triggers, waiting period, and limits |
| Medicare | Medical care for people 65 and older and some younger people with disabilities | Not covered when personal care is the only help needed; some Medicare Advantage plans offer limited in-home support |
| Medicaid | Health coverage for people with limited income and assets | May be covered through state home and community-based programs; eligibility and waitlists vary by state |
| Private health insurance | Doctor visits, hospital stays, prescriptions, and short-term skilled care | Not covered by most plans |
Many families combine sources, for example LTCi benefits with savings, or VA benefits for a senior veteran or surviving spouse. If you are counting on a particular program, confirm its rules before you build a care plan around it.
Our Medicare FAQs answer common questions about what Medicare does and does not pay for.
How Much Does Home Care Cost, and How Much Will Long-Term Care Insurance Pay?
CareScout’s 2025 Cost of Care Survey found the national median rate for non-medical in-home care was $35 per hour. Rates in your area may be higher or lower. Amada bills home care by the hour, with a minimum of 4 hours per day, and the hourly rate depends on the level of care. Our guide to senior care costs explains more.
Your out-of-pocket cost depends on how your policy pays and how much care your loved one needs.
- Daily or monthly maximum.
This is the most your policy will pay per day or per month. A policy with a $150 daily maximum could cover a 4-hour visit at $35 per hour in full, but not an 8-hour day. - Total benefit amount.
Many policies set a lifetime pool. For example, a $200 daily benefit with a 3-year benefit period creates a pool of about $219,000. Using less than the daily maximum can stretch that pool over a longer time. - Reimbursement vs. indemnity.
A reimbursement policy pays for actual care costs, up to the limit, after you submit invoices. An indemnity or cash policy pays a set amount once you qualify, regardless of what care costs. - Inflation protection.
A policy bought years ago may include a rider that has raised the daily maximum over time. Check your most recent benefits statement for the current amount. - Elimination period.
Your family pays for care until the waiting period ends.
These numbers are examples only. Your actual costs and coverage will depend on your policy. A policy review can show you exactly what your plan would pay for your loved one’s care.
How to Use Your Long-Term Care Insurance for Home Care: Step by Step
You do not need to understand every page of your policy before you start.
- Find the policy.
Locate the full contract, any riders or amendments, and the most recent benefits statement. If you cannot find it, call the insurer and request a copy. - Check the home care terms.
Look for the benefit trigger, elimination period, daily or monthly maximum, total benefit, and any provider requirements. - Call the insurer to open a claim.
Ask which forms you need, whether they will send a nurse for an assessment, and how they count the elimination period. - Get the certification and plan of care.
Ask your loved one’s doctor or another licensed practitioner to document the need for care. The insurer may also need a written plan of care. - Start care with an eligible provider.
Confirm that the home care agency meets your policy’s requirements before care begins. In many policies, the elimination period starts with the first day of paid care. - Submit care records on schedule.
Most reimbursement policies ask for invoices and caregiver notes every month. Keep copies of everything you send. - Track your benefits.
Review how much of your benefit you have used and how much remains, and update the insurer when care needs change.
A pending claim does not guarantee a payment. The insurer decides eligibility and payment under the policy terms. For a closer look at the claims process, see our guide to free LTCi claims processing.
Common Pitfalls to Avoid
- Waiting for a crisis.
Reviewing the policy before care is urgent gives you time to plan for the elimination period. - Hiring a caregiver the policy will not pay for.
Confirm provider requirements before anyone starts working. - Assuming the waiting period counts calendar days.
A service day policy can take months longer to satisfy. - Letting paperwork slip.
Missing invoices or late forms can delay reimbursement. - Stopping premium payments too early.
Many policies waive premiums once you are receiving benefits, but only after the insurer confirms it. Keep paying until you have that confirmation in writing. - Dropping coverage after a rate increase.
Ask about options such as reducing the benefit before you cancel. Each choice affects future protection. Our “Don’t Let Long-Term Care Insurance Scare You” post covers what to do when a premium increase arrives.
How Amada Makes the Process Easier
Through our LTC Concierge Service, Amada care advisors work with you and your insurer so you can focus on your loved one. Depending on your local office, we can:
- Review your policy with you, including the benefit trigger, elimination period, daily maximum, and lifetime benefit
- Set up a conference call with you and your insurance carrier
- Help you complete claim forms and gather supporting records
- Bill your insurance company directly, if you prefer
- Provide the care plans, caregiver notes, and invoices your insurer requests
- Help you track how much of your benefit remains
Amada has established relationships with many long-term care insurance carriers and third-party administrators, which can help families move through the process.
Questions to Ask Before Choosing a Home Care Provider
The provider you choose affects both the quality of care and whether your policy will pay. Ask each agency you consider:
- Licensing:
Is your agency licensed in this state for the services my loved one needs? - Policy requirements:
Do you meet the provider requirements in my LTCi policy, and have you worked with my insurance carrier before? - Caregiver screening:
Are caregivers employees of the agency? What background checks, skills assessments, and training do they complete? - Caregiver matching:
How do you match caregivers to a client’s needs, personality, and schedule? - Supervision:
Who oversees the caregiver, and how often is the care plan reviewed? - Backup care:
What happens if the regular caregiver is sick or unavailable? - Documentation:
Will you provide the care notes, plans of care, and invoices my insurer requires? - Billing:
Can you bill my insurer directly? What will I owe during the elimination period? - Liability:
Are caregivers bonded and insured, and does the agency carry workers’ compensation?
At Amada, every caregiver is a bonded and insured employee who completes a background check and skills assessment. We match caregivers based on personality, languages spoken, skill level, and hours needed.
Learn more about how an in-home caregiver can help, or read about the difference between a home care agency and a registry.
File a Free Long-Term Care Insurance Claim Now
Frequently Asked Questions
Many policies do, as long as you meet the benefit trigger and the caregiver meets the policy’s provider requirements. Most policies pay for caregivers employed by a licensed home care agency. Check your contract or ask for a policy review to confirm.
Most policies require help with at least two of the six standard activities of daily living, with the need expected to last at least 90 days. A severe cognitive impairment can also qualify on its own. Your policy spells out the exact definitions.
Yes, in most policies. A person living with Alzheimer’s disease or another form of dementia may qualify because they need supervision to stay safe, even if they can still manage some ADLs. Most insurers confirm the impairment with standardized tests.
Some policies allow it, and many do not. Others exclude family members who live in the home. Review the provider section of your policy or ask the insurer before a relative begins providing paid care.
Many policies require care from a state-licensed home care agency, not an independent caregiver. Licensing rules for home care also vary by state. Confirm both your policy’s requirements and your agency’s licensing before care starts.
An elimination period is the waiting period between meeting your benefit trigger and the start of payments. It often lasts 90 days. Some policies count calendar days, while others count only days you receive care.
Medicare does not pay for ongoing non-medical care at home when that is the only help someone needs. It may cover short-term home health care after a hospital stay when its requirements are met.
It can, but your daily maximum limits how much the policy pays. Around-the-clock care costs more than most policies’ daily maximums, so many families pay the difference or combine LTCi with other resources.
Your policy pays up to its daily or monthly maximum until you use up your total benefit. A reimbursement policy pays your actual care costs up to that limit, while an indemnity policy pays a set amount. Your most recent benefits statement lists your current limits.
Most insurers ask for a claim form, a practitioner’s statement certifying the need for care, a plan of care, and invoices or care notes from your provider. Ask your insurer for its complete list before you submit.
Many policies pay for in-home dementia support and for care in a memory care or assisted living community. Coverage depends on your policy’s terms and the care setting.
Some policies include a restoration-of-benefits rider. If your loved one recovers and goes a set period without needing care, usually 180 days, the policy may restore the benefits already used. Check your policy for this rider.
Most LTCi policies pay for covered care anywhere in the United States, as long as the new provider meets the policy’s requirements. Confirm with the insurer before a move.
How Amada Helps With Long-Term Care Insurance Claims
Amada Senior Care provides compassionate, non-medical in-home care through locally owned offices across the United States. We have helped more than 100,000 seniors and family members with home care. We also help families find and fund the care they need, from long-term care insurance to VA benefits.
For policyholders, our LTC Concierge Service brings care and claims support together. Your local Amada team can review your policy, work with your insurer on the paperwork, bill the carrier directly if you prefer, and deliver the care your loved one needs at home. You work with one team instead of coordinating a caregiver and an insurance claim on your own.
If you or a loved one has a long-term care insurance policy, contact your local Amada Senior Care office to ask about a complimentary policy review, or call 866-752-1961. One conversation can show you what your coverage includes and what to do next.
Coverage, eligibility, and claims requirements vary by policy. Amada works with most major long-term care insurance providers, and the insurer determines eligibility and payment. Services and availability vary by location. Amada Senior Care franchises are independently owned and operated. Care services are non-medical; for medical needs, consult a licensed healthcare provider. Information reflects sources reviewed in November 2026.